 English
 Français
 Español
What’s the problem?
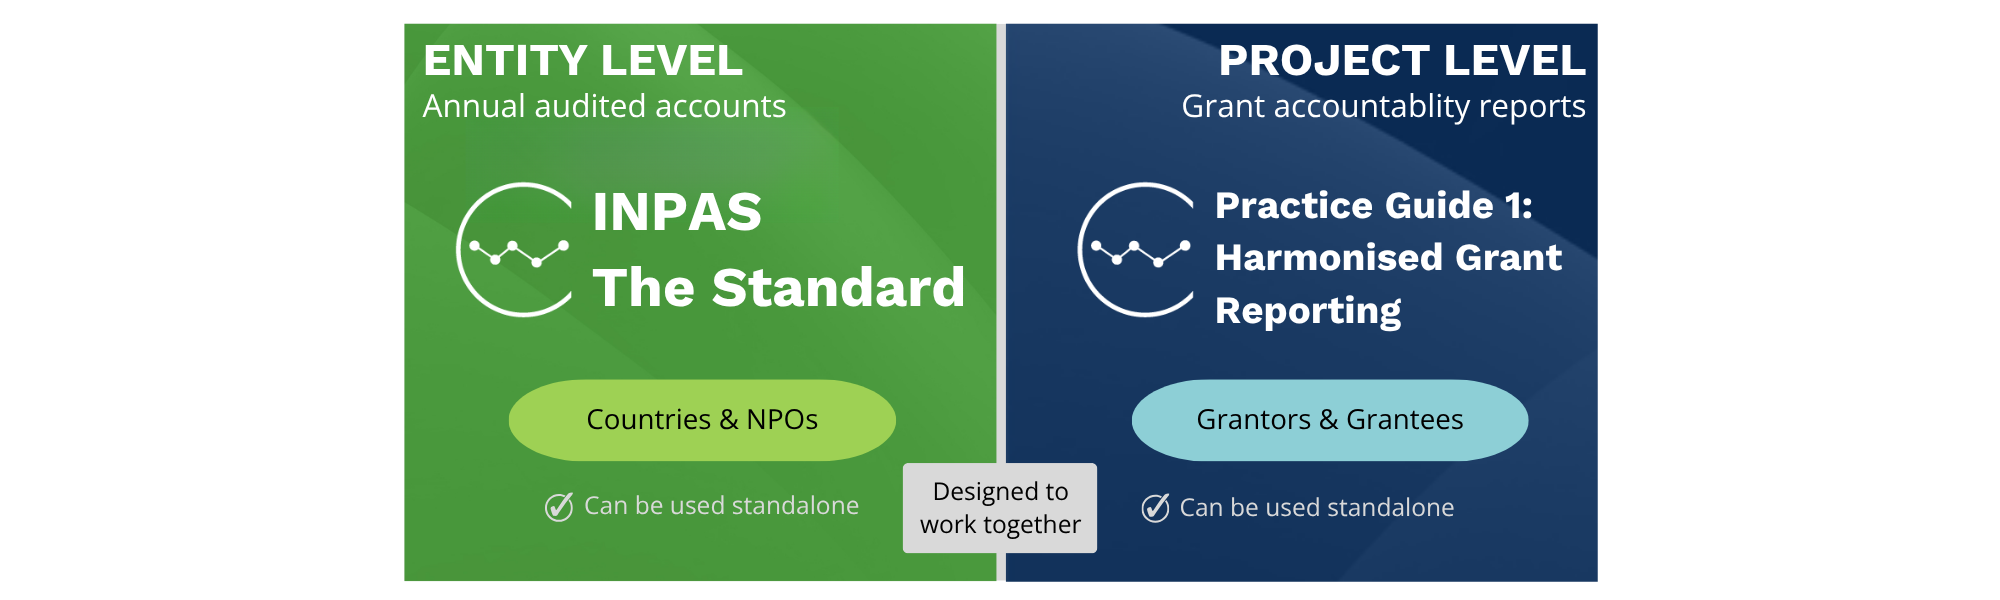
Many NPOs face challenges meeting the financial reporting requirements of multiple donors. Practice Guide 1 harmonises the presentation of grant information for donors through individual Supplementary statements. The objective of harmonised grant reporting is to present key auditable information about a set of an NPO’s activities that is useful to individual stakeholders (including donors).
Practice Guide 1 will help to:
- Improve consistency and comparability across donor reports
- Support better communication with funders and other stakeholders
- Clarify how grant-level reporting fits within the whole-of-NPO financial picture

Key features and requirements
INPAS Practice Guide 1 requires Supplementary statements that:
- disclose defined categories of income and expenses
- are accrual-based
- are supported by notes that explain the purpose and scope of the Supplementary statement
- are reconciled to the opening and closing balances for the funds related to that specified activity to the financial statements.
The expense line items cover the main categories of expense typically required by grantors to report on the direct costs of an activity.
Practice Guide 1:
- can be used for a single specified activity or a group of specified activities
- prescribes the line items that can be used to categorise income and expenses
- allows support costs to be shown as a separate line item or apportioned to the direct costs, giving flexibility to meet donor requirements
These variants include:
- comparison to budget
- multiple grants
- multiple time periods
- different currencies
This part of the Supplementary statements allows:
- the replacement of accrual-based information such as depreciation, amortisation and inventory expenses with cash costs incurred
- allows this option to be exercised for capital costs, inventory or both
- However, they must be clearly presented as not being part of the General Purpose Financial Report
- The scope of audit assurance of the Supplementary statements must be clear, including whether any of these have been audited
The Value proposition – Doing more with less
INPAS and Practice Guide 1 when used together enable:
- more useful general-purpose financial reports for a range of users – including donors, regulators, and boards
- streamlined donor reporting – one standard format reduces reporting burden
- stronger alignment between grant reporting and full financial accounts, building funder confidence and transparency
For NPOs
Practice Guide1 simplifies and standardises financial reporting, helping organisations manage sustainability, meet donor requirements, and strengthen funding proposals.
For Funders
Practice Guide 1 provides a reconciliation of grant reports to the main audited accounts, a standard approach that means quicker and more accurate reports from grantees, and sufficient flexibility to ensure your information needs are met.
For Auditors
Practice Guide 1offers a consistent and structured reporting framework, including reconciliation to the main accounts, reducing ambiguity and strengthening assurance.
INPAS Practice Guide 1 has universal use
This Practice Guide is essential for NPOs that provide grant reports to multiple donors. It provides guidance for the completion of a standardised Supplementary statement format. It is designed to be consistent with the principles in INPAS, but can be used with any accrual-based general purpose financial statements.